Car vs Motorcycle Insurance: Costs, Coverage and Key Differences

Not sure whether to go for a car or a motorcycle—or wondering which one is more expensive to insure? Both need insurance by law, but the costs, coverage, and risks aren’t the same. Read Motorscan’s complete guide to discover the key differences, how premiums are set, and money-saving tips that will help you pick the right cover with confidence.
When it comes to protecting your vehicle on UK roads, both cars and motorcycles must have a minimum of third-party insurance by law. This ensures that if you cause damage or injury to others in an accident, you’re legally covered. Beyond that, however, the similarities end. Car and motorcycle insurance can look very different, with premiums, coverage options, and influencing factors varying depending on the type of vehicle, how it’s used, and even where it’s kept. Understanding these differences can help you make smarter choices, avoid overpaying, and ensure you’ve got the right level of protection in place.
Insurance Calculation Differences
Insurance premiums for cars and motorcycles are both based on risk, likelihood of claims, and repair costs, but the factors insurers focus on often differ. Motorcycles are generally considered higher risk due to rider vulnerability, while cars benefit from added safety features and lower injury likelihood. These differences help explain why premiums can vary so much.
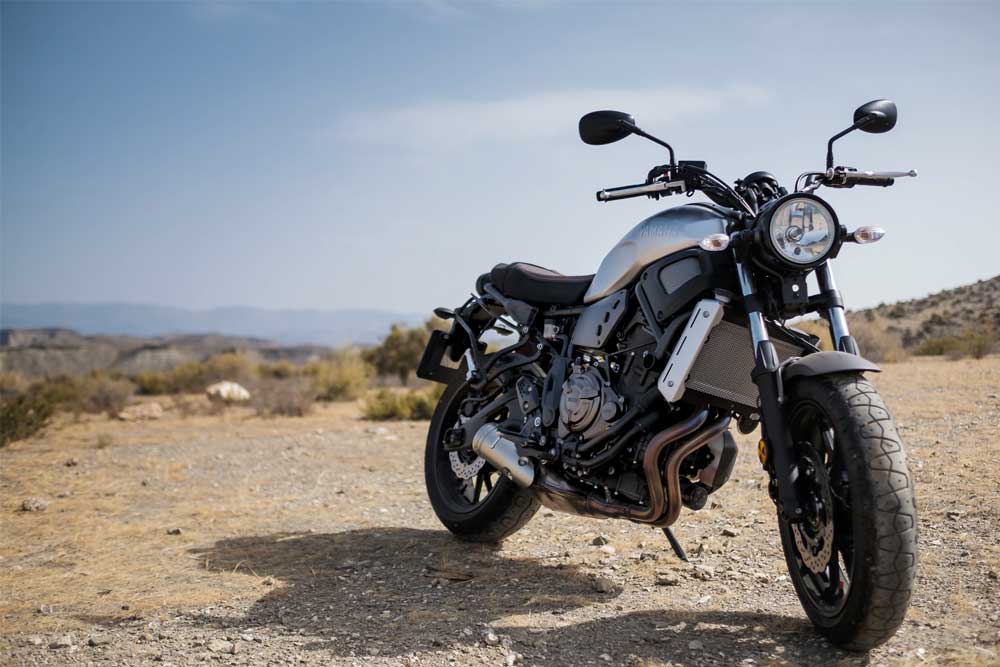
- Motorcycle Factors
- The size of a bike’s engine plays a significant role in how much you’ll pay: bigger engines usually mean higher premiums because of the increased speed and risk.
- The type of bike affects costs, with sports bikes generally more expensive to insure than touring or commuter models, which are seen as safer and more predictable on the road.
- How and where you store your bike also matters. Garaged bikes are less likely to be stolen, so insurers often charge less.
- Seasonal usage can make a difference too, with many riders opting to store their bike over winter and choosing “laid-up” policies, thus reducing premiums.
- Car Factors
- Every vehicle in the UK is placed in an insurance group, which influences car premiums. These are based on engine size, performance, and repair costs, and mean that lower group cars are cheaper to insure.
- Modern safety features, like airbags and automatic braking, help lower premiums, as cars with higher crash-test ratings reduce the insurer’s risk.
- Families or households with multiple vehicles can benefit from discounts given under multi-car policies, which means drivers can benefit from lower premiums.
- Cost Comparisons
- Premiums vary widely for both cars and motorcycles, with small commuter bikes costing only a few hundred pounds a year to insure, while high-powered sports bikes can run into the thousands. Cars follow a similar pattern, with budget hatchbacks at the lower end and high-end models costing £1,500 or more annually.
- Age and experience affect both types of insurance, with young or inexperienced riders or drivers facing particularly high premiums due to increased accident risk.
- Where you live also matters, with urban areas with more traffic and theft often attracting higher premiums than more rural locations.
Coverage Differences
- Motorcycle insurance
Bike insurance often comes with extras designed for riders. It can cover things like helmets and protective clothing, which are expensive to replace if damaged. Many policies won’t cover track days, and some let you pause your cover in winter if the bike isn’t being used. Insurers also pay close attention to upgrades or modifications, as these can change the bike’s value and risk level.
Car insurance
Typically, this type of insurance offers perks that make life easier, such as a courtesy car while your vehicle is being repaired and the option to add multiple cars and drivers to a single policy. Standard commuting and personal use are usually automatically included, but if you need to drive for work, adding business use is a common extra.
- Claims and Risk Factors
Motorcyclists unsurprisingly face a higher risk of injury, which directly impacts premiums. Determining fault can also differ with accidents involving bikes, which typically require specialist assessments. Cars, on the other hand, are generally easier to repair and replace, and the claims process can be more straightforward.
Repair costs for bikes can be costly, depending on parts and labour. Cars, especially standard models, are often cheaper to fix because parts are widely available and repairs are more straightforward.
Money-Saving Tips
Organising insurance can be complex and expensive, but there are practical ways to reduce premiums for both vehicle types. Motorcycle riders can benefit from advanced riding courses, such as IAM or RoSPA, which demonstrate safer riding and can lower premiums. Investing in security, like locks, alarms, and secure garage storage, can also help.
Car owners can take advantage of Pass Plus schemes, multi-car policies, and telematics (black box) insurance, which reward safer driving habits with lower premiums. In both cases, a few strategic choices can make a noticeable difference to your annual insurance bill without compromising protection.
Read more...
2023 Ultimate Guide to Car Insurance
Most of us look to obtain the cheapest car insurance possible for the cover we're after, and the easiest way to do this is to visit a car insurance comparison site. Read our guide on how to get cheap car insurance